When you visit our website, information may be stored or recovered on your device, mainly in the form of cookies. We use essential cookies to ensure the website works as it should, and statistical and marketing cookies for audience measurement and content customisation purposes. We rely on Google for statistical and marketing cookies in order to measure website performance and display relevant advertising. For more information on this, please also refer to the Google policy on Business Data Responsibility.
From the Cookie Management Centre, you can set your preferences with respect to the use of cookies: accept or reject certain categories, accept all, or reject all. For detailed information on all cookies used across these three categories, please refer to our Cookie Policy.
Please note that blocking certain cookies may affect your experience and the services offered.
Essential cookies Always active
Essential cookies help the website to work as it should by enabling necessary functionalities, such as navigating between pages and accessing secure areas. These cannot be disabled in our systems.
Statistical cookies
Statistical cookies help us understand how visitors interact with our site by collecting and communicating browsing information. They make it possible to identify the most and least visited pages and to improve the overall performance of the site.
Marketing cookies
Marketing cookies are used to display relevant advertising and measure the performance of campaigns. If you choose not to allow these cookies, you will continue to see ads, but they will be less relevant to your interests.
Choose the purposes for which we may use Google products to collect and use your data:
User storage: to technically permit advertising functionality.
User data for advertising: to optimise our advertising campaigns.
Ad customisation: to tailor advertising to your interests.
AI is a primary driver of the current manufacturing revival across regions and sectors. A more competitive, multipolar world is also leading to increased defence spending and industrial activity
Protectionist US trade policies have seen some manufacturing repatriated; crucially they have spurred other countries to boost goods exports and production, taking advantage of more stable US tariff policies than in 2025
Countries are investing more in energy security given a combination of geopolitical tensions, oil price volatility and rising energy demand
A unique investment cycle spanning technology, defence, energy and infrastructure is broadening corporate earnings growth and underpins our global equity overweight.
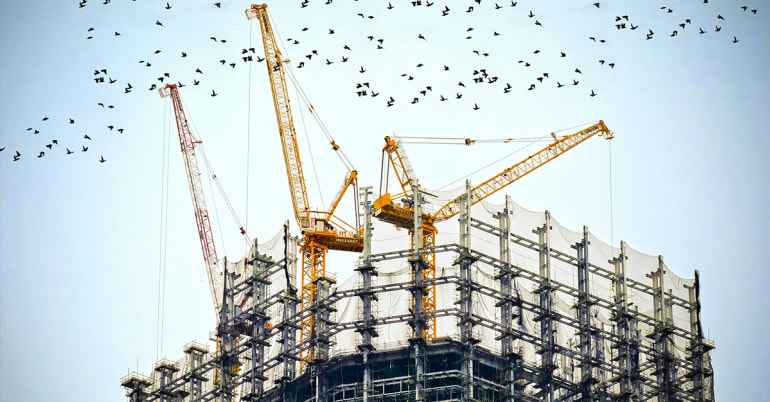
A manufacturing rebound is in motion, spreading from emerging markets in early 2026 into developed economies as well. In the US, Europe and Asia, manufacturing activity is growing across different sectors, from chemicals, pharmaceuticals, machinery, construction to defence and shipping. This is rooted in four different but interlinked developments.
The first is the multi-trillion-dollar capital spending cycle linked to artificial intelligence (AI). As the world adapts to this revolutionary technology and its implications across sectors, countries are upgrading their domestic infrastructure.
As a result, AI is driving a large and sustained capital spending boom. This is boosting construction activity, energy capacity and distribution upgrades, and growth in the number of data centres globally – as well as the computers, servers and equipment to fill them.
Sign up for our newsletter
A more fractured and competitive world means that countries see these upgrades as strategic priorities. This is creating a global, rather than a regional, recovery in industrial activity. Unlike the China-centred industrial boom that followed the country’s accession to the World Trade Organisation in 2001, this time the AI-capex-led industrial boom is broadly distributed geographically.
The need for defence and homeland security… is likely to continue driving… orders for defence equipment
Rising security needs
A second driver of the rebound is linked to more conflictual international relations, which are leading to a surge in defence spending and related industrial activity. Governments involved in conflicts, including the US, are pushing manufacturers to replenish military assets, while those with the fiscal ability, including Germany, have raised defence spending at a time when Europe is increasingly taking responsibility for its own security. Recent new manufacturing orders in Germany, for example, were dominated by large-scale government orders for transport equipment.
The recently-concluded defence pact between Pakistan, Turkey and Saudi Arabia demonstrates the global nature of the need for defence and homeland security, and is likely to continue driving foreign and domestic orders for defence equipment exporters. Estimates of the share of defence in global industrial production are now around 4-5%. Counting dual-use equipment, which can serve both civilian and military purposes, the estimated share may be as large as 8-10%.
US tariffs and trade protectionism
A more protectionist US, applying new trade policies, has added a third source of industrial activity. US tariffs have helped create the economic conditions and incentives for an industrial repatriation that can be seen in the ISM index. Many international companies looking to sell their products into the world’s biggest consumer market have invested in US production capacity following the administration’s tariff announcements in April 2025.
More surprisingly, US policy has also unleashed industrial activity elsewhere, as countries have sought to take advantage of more stable US tariffs after a tumultuous 2025. China’s goods exports have soared, with vehicles, electrical machinery and equipment as the driving force.
US policy has also unleashed industrial activity elsewhere…
Even small export-led countries like Switzerland – which had faced US tariffs of 39% that were later reduced to 15% – have seen a revival of their industry and exports. In the second quarter, chemicals and pharmaceuticals made the largest contribution to growth, with a 4.5% expansion across broader manufacturing, as companies raced to produce and export during a window of more predictable tariffs. The result was an exceptionally strong growth rebound, with real GDP growth in Switzerland rising 1.5% in the second quarter.
Energy security and oil price volatility
Oil price volatility and threats to key strategic supply routes and chokepoints have also seen energy security rise up government agendas. With the Middle East conflict still unresolved, and the Russia-Ukraine war having rewired Europe’s energy supply chains, crude oil prices are back to February 2022 levels.
While oil prices may fall rapidly if shipping volumes through Hormuz recover, even if they do not return to pre-war levels, the incentive for countries to become less dependent on fossil fuel imports and more self-sufficient in energy will remain. Geopolitical tensions are converging with rising energy demand, including for AI, while renewable solutions have become increasingly cost competitive. This combination of factors has unleashed investment in energy security, including renewables, nuclear, gas and even coal, all adding to industrial demand. The International Energy Agency estimates that global energy investment will reach a record USD 3.4 trillion in 2026.
A competitive multipolar world with rising investment can benefit a broader base of companies and sectors
Equity market implications
For much of the last three years, equity market performance has been highly concentrated, driven by only a few sectors and companies, notably US tech stocks. Yet the equity market rally of 2026 has been driven by a much broader base of companies. Second-quarter earnings showed strong positive surprises across sectors and regions, with financials and energy in particular joining AI as key profit drivers.
The key lesson is that a competitive multipolar world with rising investment can benefit a broader base of companies and sectors. Despite the considerable risks and uncertainties, a unique capital spending cycle across technology, defence, energy and infrastructure is boosting corporate profits.
A strong earnings outlook underpins our portfolio overweight to equities in both developed and emerging markets. In our view, the recent fall in valuations induced by rising bond yields offers a good buffer for stocks to continue rising, if earnings expectations are realised in the coming months, and into 2027.
This is a marketing communication issued by Bank Lombard Odier & Co Ltd (hereinafter “Lombard Odier”).
It is not intended for distribution, publication, or use in any jurisdiction where such distribution, publication, or use would be unlawful, nor is it aimed at any person or entity to whom it would be unlawful to address such a marketing communication.

share.