When you visit our website, information may be stored or recovered on your device, mainly in the form of cookies. We use essential cookies to ensure the website works as it should, and statistical and marketing cookies for audience measurement and content customisation purposes. We rely on Google for statistical and marketing cookies in order to measure website performance and display relevant advertising. For more information on this, please also refer to the Google policy on Business Data Responsibility.
From the Cookie Management Centre, you can set your preferences with respect to the use of cookies: accept or reject certain categories, accept all, or reject all. For detailed information on all cookies used across these three categories, please refer to our Cookie Policy.
Please note that blocking certain cookies may affect your experience and the services offered.
Essential cookies Always active
Essential cookies help the website to work as it should by enabling necessary functionalities, such as navigating between pages and accessing secure areas. These cannot be disabled in our systems.
Statistical cookies
Statistical cookies help us understand how visitors interact with our site by collecting and communicating browsing information. They make it possible to identify the most and least visited pages and to improve the overall performance of the site.
Marketing cookies
Marketing cookies are used to display relevant advertising and measure the performance of campaigns. If you choose not to allow these cookies, you will continue to see ads, but they will be less relevant to your interests.
Choose the purposes for which we may use Google products to collect and use your data:
User storage: to technically permit advertising functionality.
User data for advertising: to optimise our advertising campaigns.
Ad customisation: to tailor advertising to your interests.
US midterms point to volatility, then investment opportunities
Dr. Luca Bindelli
Head of Investment Strategy
key takeaways.
Election-related volatility may rise temporarily, but reduced legislative uncertainty should ultimately support risk assets
A modest fiscal drag in 2027 and reduced policy uncertainty could ease pressure on long-term yields, supporting fixed income
Post-election relief could also support equities, although earnings, margins and the trajectory of interest rates will remain more important
Narrower yield differentials could weigh on the dollar, although stronger institutional checks may support it against low-yielding currencies. Gold remains a useful diversifier in portfolios.
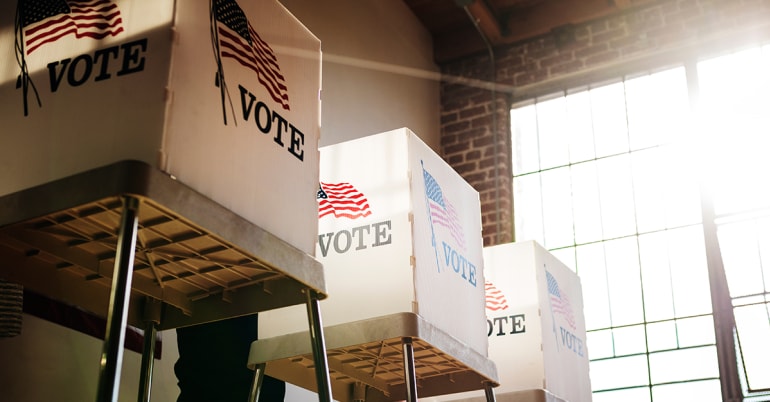
Our core view on the 2026 US midterm elections is that they are likely to narrow the administration’s governing mandate rather than fundamentally alter the direction of economic policy. A shift from the previous Republican majority to a Democratic majority in the House is our base case, while control of the Senate has become more competitive.
We therefore expect some form of divided government, which would limit the scope for major new tax or spending legislation while leaving trade and foreign policy largely under the president’s executive control. Fiscal policy would remain on its existing course, shifting over the coming quarters from a significant support for growth towards a modest headwind.
While the election may generate volatility, the more durable investment consequence is likely to be a reduction in legislative uncertainty once the vote has passed. For financial assets, the path of inflation, monetary policy, the strength of the US economy and corporate earnings, will remain more important than the election result. Yet all else being equal, a divided government post-midterms has often marked the beginning of a more constructive three-month period for government bonds, high-quality corporate bonds and equities.
A divided government post-midterms has often marked the beginning of a more constructive three-month period for government bonds, high-quality corporate bonds and equities
Government bonds tend to benefit
Historically, US midterm elections have marked a constructive turning point for fixed income. On average, 10-year US Treasury yields have declined by about 20-25 basis points (bps) over the three months post-election, and two-year yields by around 10 bps. This time, a more predictable fiscal path under a divided government, and a modest fiscal drag should ease the upward pressure on longer-dated yields. Part of the political and fiscal risk premium embedded in longer bond maturities could unwind, while short-dated yields would remain more closely tied to monetary policy.
Sign up for our newsletter
German Bund yields have also tended to decline after US midterms, although less than Treasury yields. This suggests that historical bond rallies partly reflect a broader reduction in macroeconomic and policy uncertainty. Global government bonds could therefore benefit, with the strongest sensitivity in the US market.
This does not imply a rapid or uninterrupted bond rally post-election. Tariffs remain within the administration’s executive authority and, together with geopolitical and oil-price risks, could sustain inflation uncertainty, which could partly offset the benefits of fiscal restraint. Government shutdowns or funding disputes could also temporarily increase volatility and long-dated yields.
A more predictable fiscal path under a divided government, and a modest fiscal drag should ease the upward pressure on longer-dated yields
However, we continue to envisage a progressive disinflation trend in the US. While we expect one further policy rate hike from the Federal Reserve this year, we do not anticipate current market expectations for nearly three more 25 bp hikes in 2027 to materialise. As such, we think currently elevated US sovereign bond yields offer good compensation for risk and we continue to favour 5-to-7-year Treasuries.
Corporate bond markets have also performed well historically after midterm elections. Investment-grade spreads – or the additional yields on offer over government bonds – have typically tightened progressively, while high-yield spreads have compressed more sharply. Falling government bond yields could support total returns, and reduced electoral uncertainty could encourage investors to redeploy cash, and rebuild risk exposure. Divided government may also reassure corporate bond investors by limiting abrupt fiscal or regulatory changes. However, the historical pattern should not be interpreted as a buying signal by itself. We remain neutral on corporate bonds given already tight spreads, and favour selective exposures, including issuers with strong free cash flow, manageable refinancing needs and limited exposure to tariff-related cost pressures.
Political relief helps but earnings remain key
Equity markets have often been volatile before midterms, recording a low roughly one month before the election, and strengthening afterwards. US equity market volatility has also tended to rise prior to the midterms, peaking around one month beforehand, before trending lower. Today, volatility is below historical midterm averages, suggesting that it could rise before November. However, future contracts are already pricing in volatility normalising in three months’ time closer to typical post-election levels.
Overall, fading electoral uncertainty can support risk appetite, while a divided government would reduce the likelihood of new, disruptive legislation. In 2026, election-related weakness would therefore be more likely to create a tactical opportunity than signal more downside risk ahead, provided the economic and earnings outlook remains intact.
That said, equities should not depend on a post-election boost on the fiscal front. Market direction will instead hinge on whether private-sector demand, investment and earnings can offset weaker fiscal support. This backdrop favours selectivity. Companies with strong balance sheets, substantial free cash flow, durable margins and visible earnings growth should retain a valuation premium and outperform businesses reliant on government spending.
Election-related weakness in equities would be more likely to create a tactical opportunity than signal more downside risk ahead
Lower Treasury yields would generally support growth stocks such as tech, communication services, consumer discretionary and small capitalisations, by making future earnings look more attractive. However, the reason for the decline in yields matters. An orderly decline in yields, driven by lower inflation and gradual policy normalisation, would be favourable. Industrials and capital-goods companies should remain supported by previously approved investment incentives, although the absence of new legislation limits further fiscal upside. Healthcare may benefit from lower legislative uncertainty. Financials have faced a mixed outlook around previous midterms that have resulted in a divided government as the difference between long and short-dated bond yields narrows. But strong loan growth and capital markets could provide support this time. Finally, energy and defence should remain more influenced by executive policy and geopolitics than by congressional control.
US small caps could benefit disproportionately from lower short-term Treasury yields and we retain an overweight to small capitalisation stocks globally in portfolios. Overall, the midterms should be viewed as a potential source of near-term volatility but not create a lasting market headwind. Beyond the election, profit margins, earnings growth and interest rates will remain the dominant drivers for equity markets.
Neutral dollar, marginally stronger gold
The implications for the US dollar are less clear-cut. Lower Treasury yields would narrow interest-rate differentials with other countries, which would weaken the dollar, particularly against currencies backed by improving domestic fundamentals. Historically, the approach of midterm elections has tended to trigger a reversal of prior gains in emerging market currencies. However, assuming the broader macroeconomic backdrop remains unchanged, the prevailing environment of resilient economic growth, persistent inflation, and elevated yields should continue to favour high-yielding emerging market currencies, making any pre-election volatility a potential opportunity.
Although a divided government could increase political friction and revive concerns about government shutdowns, we believe the more important implication would be stronger checks and balances on future Federal Reserve Board appointments, as nominations would require support from at least some Democratic senators. This would reduce the likelihood of policies perceived as undermining monetary credibility and could support the dollar against low-yielding currencies such as the euro or Swiss franc.
Although a divided government could increase political friction and revive concerns about government shutdowns, we believe the more important implication would be stronger checks and balances on future Federal Reserve Board appointments
Lower real yields after the election would support gold, while any potential disputes over the electoral process, government shutdowns or geopolitical escalation could reinforce demand for portfolio hedges. Also, longer-term concerns about US fiscal sustainability will not disappear simply because near-term fiscal policy becomes more constrained. We believe gold can therefore continue to play a useful role in portfolio diversification.
Stay invested and favour equities
In conclusion, the principal importance of the US midterms lies in the transition from political uncertainty to greater policy visibility. The expected combination of a divided government and resilient growth should support fixed income and we continue to favour 5–to-7-year US Treasuries. We remain neutral overall in sovereign bonds and keep an overweight to emerging market US-dollar denominated bonds, which offer higher comparable yields and stable spreads over US sovereign debt.
In equities, volatility should lead way to more gains, helped by a backdrop of durable and strong earnings. We remain overweight global equities, with a preference for emerging markets, Japan, and small capitalisation stocks.
CIO Office Viewpoint
US midterms point to volatility, then investment opportunities
This is a marketing communication issued by Bank Lombard Odier & Co Ltd (hereinafter “Lombard Odier”).
It is not intended for distribution, publication, or use in any jurisdiction where such distribution, publication, or use would be unlawful, nor is it aimed at any person or entity to whom it would be unlawful to address such a marketing communication.

share.