When you visit our website, information may be stored or recovered on your device, mainly in the form of cookies. We use essential cookies to ensure the website works as it should, and statistical and marketing cookies for audience measurement and content customisation purposes. We rely on Google for statistical and marketing cookies in order to measure website performance and display relevant advertising. For more information on this, please also refer to the Google policy on Business Data Responsibility.
From the Cookie Management Centre, you can set your preferences with respect to the use of cookies: accept or reject certain categories, accept all, or reject all. For detailed information on all cookies used across these three categories, please refer to our Cookie Policy.
Please note that blocking certain cookies may affect your experience and the services offered.
Essential cookies Always active
Essential cookies help the website to work as it should by enabling necessary functionalities, such as navigating between pages and accessing secure areas. These cannot be disabled in our systems.
Statistical cookies
Statistical cookies help us understand how visitors interact with our site by collecting and communicating browsing information. They make it possible to identify the most and least visited pages and to improve the overall performance of the site.
Marketing cookies
Marketing cookies are used to display relevant advertising and measure the performance of campaigns. If you choose not to allow these cookies, you will continue to see ads, but they will be less relevant to your interests.
Choose the purposes for which we may use Google products to collect and use your data:
User storage: to technically permit advertising functionality.
User data for advertising: to optimise our advertising campaigns.
Ad customisation: to tailor advertising to your interests.
Global earnings growth remains strong and broad-based, although the acceleration seen in recent quarters is beginning to moderate
Energy has provided an important boost to profits, particularly in Europe, but its contribution is likely to fade as oil prices ease and base effects become less supportive
AI remains the dominant earnings and investment theme, with evidence of monetisation continuing to strengthen, despite recent market volatility
We expect earnings leadership to broaden beyond technology over the coming year. We maintain a preference for technology, utilities, financials and materials, as well as the US, Japan, select emerging markets and small capitalisations.
The global earnings cycle remains resilient. As third-quarter corporate reporting concludes, companies continue to deliver earnings growth rates that are unusually strong by historical standards. While the pace of earnings improvements is no longer accelerating, the breadth and strength of growth suggest that corporate fundamentals remain supportive for risk assets.
At the time of publication, around 60% of the MSCI All Country World Index (ACWI) companies have reported results, with earnings per share (EPS) on track to rise by approximately 32% year-on-year. This represents a slowing from the second quarter’s 46% pace, but the underlying picture is constructive, and once the effects of investment-related gains are removed, earnings growth is broadly unchanged from the previous three-month period.
Importantly, growth continues to be driven by a combination of rising revenues and expanding profit margins across most sectors and regions. Earnings surprises are also still positive, although the scale of outperformance has normalised from the exceptional levels seen earlier in the cycle. Taken together, these trends suggest that the earnings expansion is intact, even as the period of accelerating growth begins to fade.
Sign up for our newsletter
Energy has contributed a quarter of earnings growth globally. Higher oil prices, driven by renewed tensions in the Middle East and rising shipping costs, lifted Brent crude prices by 32% year-on-year through the third quarter. This boosted profits in the energy sector by 93% from a year ago. The impact has been particularly visible in Europe and the UK, which have high exposure to the sector, and earnings growth has risen 27% for the MSCI EMU and 55% for MSCI UK, with energy alone accounting for 40% and 75% of that growth respectively.
Energy has contributed a quarter of earnings growth globally
A gradual easing of energy disruptions, lower oil prices and diminishing year-on-year ‘base effects’ will weigh on the sector and energy-exposed markets towards the middle of 2027. Nevertheless, the need to replenish depleted strategic reserves should provide a degree of support for oil prices and profitability.
US and AI remain the core driver
The main driver of global earnings growth remains the US technology sector and buildout of AI infrastructure. Earnings growth within the S&P 500 is approximately 32% year-on-year, a little ahead of analysts’ forecasts, and 34% for the MSCI USA index. More than half of this increase has been generated by the information technology sector, which accounts for 56% of total earnings growth, largely driven by semiconductor companies.
Nevertheless, semiconductor stocks have retreated more than 20% over the course of the quarter’s earnings season. A combination of crowded investor positioning, profit-taking and adverse headlines have weighed on performance, despite the continued strength in the sector’s underlying earnings.
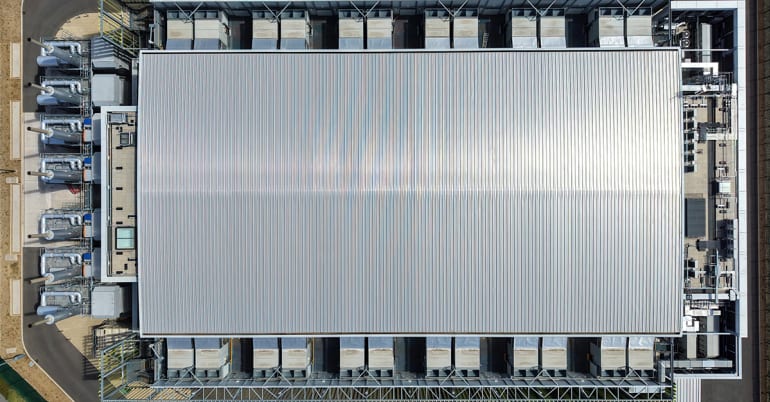
In our view, the recent selloff is overdone, and we see it as an investment opportunity. Concerns around financing, particularly around so-called neocloud firms that build data centres and rent out computing capacity, have risen amid higher credit-default protection costs and a rise in bond yields. However, these businesses typically finance projects at the project level, locking in both costs and revenues while retaining a calculable residual free cash flow. Moreover, neoclouds account for only 6% of overall AI-related capital expenditure. Any shortfall would therefore likely be absorbed by hyperscalers.
Hyperscalers’ cloud revenues continued to accelerate
Some recent hyperscalers’ earnings have fallen short of estimates, adding to concerns around AI monetisation. However, these disappointments were largely driven by one-off charges and currency effects rather than any meaningful deterioration in AI-related demand. Hyperscalers’ cloud revenues continued to accelerate despite their larger revenue base, and margins edged higher.
Some estimates suggest that current AI investment levels would require USD 3-to-4trillion of additional annual revenue by the early 2030s. While challenging, such targets appear achievable given current revenue growth trajectories. Hyperscalers are collectively already on track to generate revenues approaching USD 2 trillion in 2026 and consensus forecasts see revenue growth of around 26% per year through 2028. Even assuming growth slows to 20% annually after that, hyperscaler revenues would reach roughly USD 6.5 trillion by 2032, which is USD 4.5 trillion higher than today.$
Meanwhile, the economics of AI’s infrastructure build-out remain encouraging. The cost of generating AI output, measured by token costs, kept falling in the third quarter, alongside rising rental rates for graphics processing units (GPUs). This points to a rapid increase in demand for AI computing power and suggests that efficiency gains continue to stimulate, rather than constrain, overall usage. At the same time, cloud companies report payback periods for GPUs of around three years or less, well below the estimated five-to-six-year useful lifespan of the equipment.
Midterms cast a data-centre shadow
Since the start of earnings season capex estimates have continued to rise, reflecting these strong AI fundamentals. While supply constraints are limiting upgrades to analysts’ full-year 2026 estimates, expectations for 2027 and 2028 have been lifted by more than USD 270 billion across hyperscalers and neoclouds, to well above USD 1.5 trillion and USD 1.6 tn, respectively.
However, markets have grown more sceptical of such estimates following the Democrats’ victories in the US midterm election. While a lack of a Democrat two-thirds ‘supermajority’ in the Senate will limit their ability to enact major changes at the federal level, gubernatorial victories in key states for data-centre buildout increase the potential for project delays.
Construction and funding for 2027 look largely locked-in
These concerns may increase marginal costs, but we believe that growing demand for AI services will ultimately support pragmatic solutions. Existing construction programmes and funding for 2027 also look largely locked-in, limiting the near-term impact on investment spending.
AI also lifts Asia as capex broadens
Beyond the US, AI-driven growth is increasingly benefiting economies across Asia, especially markets such as Taiwan, South Korea and Japan, which have a high share of semiconductor and manufacturing names. In Japan, one business will have an outsized impact; investment firm SoftBank Group’s results are expected to shave 17 percentage points from the country’s earnings growth.
These markets continue to record strong underlying earnings performance, supported by semiconductor demand and broader technology investment. Corporate-governance reforms are providing an additional tailwind, particularly in Japan, where share buyback activity remains robust, and shareholder returns continue to improve.
More broadly, the capital-expenditure cycle is expanding beyond mega-cap technology names. Corporate investment growth accelerated 10% during the third quarter compared with a year ago, and consensus estimates for the S&P 500 point to 50% year-on-year capex growth in the third quarter of 2026, up from 37% in the second quarter.
Industrial companies, electrical-equipment manufacturers and machinery producers are seeing rapidly growing order books as demand linked to data centres and power infrastructure rises. Financials, materials and some industrial segments also remain strong, although financial stocks face greater competition for deposits and weaker-than-expected fixed income trading.
Emerging markets are recording broad-based earnings growth, surpassing developed market peers
In contrast, consumer-related sectors remain the weakest area in equity markets, although spending patterns are resilient. Luxury goods, however, reflect sluggish demand from Chinese consumers and the ongoing challenges in the country’s property markets.
Emerging markets are recording broad-based earnings growth, surpassing developed market peers, supported by AI-related demand and improving domestic activity. Beyond semiconductor and energy-heavy markets, India has delivered strong earnings momentum, ahead of expectations, with the MSCI China forecast to deliver earnings growth of around 9% as consumer-oriented sectors emerge from six consecutive quarters of earnings declines.
Looking ahead, we expect global earnings growth to remain robust, although the composition of that growth is likely to evolve. AI will remain the most important structural driver, but its dominance should gradually diminish as a maturing AI buildout, lower interest rates, easing energy costs and resilient economic activity support a broader range of sectors. As a result, the earnings cycle appears set to become more balanced rather than weaker, with technology setting the pace, and opportunities emerging across industrials, financials and selected emerging market equities. We maintain an overweight allocation to global equities, with a preference, beyond IT, for utilities, financials and materials. At the regional level, we continue to favour the US and Japan, as well as pro-cyclical small capitalisations, which have delivered better-than-expected earnings. We also maintain a constructive view on emerging markets where earnings momentum remains particularly strong.
This is a marketing communication issued by Bank Lombard Odier & Co Ltd (hereinafter “Lombard Odier”).
It is not intended for distribution, publication, or use in any jurisdiction where such distribution, publication, or use would be unlawful, nor is it aimed at any person or entity to whom it would be unlawful to address such a marketing communication.


share.